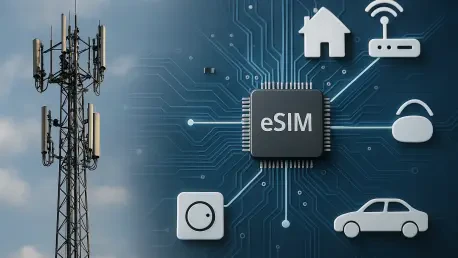
Infrastructure growth is currently outstripping immediate device deployment, indicating a period of ecosystem readiness before the next major wave of adoption. This divergence highlights a massive build-out in digital foundations that far exceeds the current pace of physical hardware activation across the globe. As the industry moves into the latter half of the year, the focus has shifted from theoretical frameworks to the practical deployment of server-side capabilities. Data from recent market assessments indicates that the telecommunications sector is prioritizing the establishment of robust, interoperable platforms that can support a massive influx of secure credentials. This proactive approach by mobile network operators and platform providers suggests a strategic decision to eliminate potential bottlenecks before the mass-market transition to digital-first connectivity becomes unavoidable. By investing heavily in backend systems today, stakeholders are ensuring that when the volume of connected devices eventually spikes, the underlying technical architecture will be capable of handling the load without compromising security or service reliability.
The Strategic Shift Toward Remote Provisioning Standards
The monumental surge in platforms supporting the GSMA SGP.32 specification represents a defining shift in how industrial sensors and smart meters are managed globally. During the first six months of the current year, the number of eSIM Subscription Manager platforms compatible with this standard grew fivefold, surpassing the cumulative totals recorded during the previous calendar year. This specific technical evolution is critical because it solves the long-standing problem of managing “headless” devices that lack a user interface for manual configuration or network switching. By introducing a remote architecture specifically tailored for the Internet of Things, the industry has removed the necessity for physical intervention or complex, proprietary workarounds. This expansion of infrastructure ensures that original equipment manufacturers can now design products for a global market without worrying about the localized logistics of cellular connectivity, as the ability to switch providers over the air is now becoming a baseline feature rather than a luxury.
Beyond the technical specifications, the rapid maturation of the SGP.32 ecosystem offers a significant strategic advantage for enterprises managing large-scale fleets of connected assets. As the technical barriers to interoperability continue to fade, businesses are finding themselves with more leverage when negotiating with connectivity providers, as they are no longer locked into a single vendor’s proprietary management platform. This shift allows for a much more agile approach to global deployment, where devices can be manufactured with a single generic credential and then localized dynamically based on the specific network conditions of their final destination. However, while the technical capability is now widespread, the operational implementation still requires careful navigation to ensure that fleet management remains consistent across different regions. Organizations are beginning to realize that the availability of these platforms is only the first step toward a fully automated lifecycle, requiring a renewed focus on integrating these digital tools into existing supply chains.
Global Regulatory Drivers and Consumer Market Maturity
In the consumer sector, the momentum for digital SIM adoption has reached an all-time high, driven largely by significant regulatory milestones in major global markets. The most notable development has been the opening of the Chinese market, where domestic authorities recently granted approval for major mobile operators to offer eSIM services to their vast subscriber bases. This policy shift has acted as a massive catalyst, resulting in a volume of profile downloads in the first half of the current year that nearly matches the total activity seen throughout all of the previous year. As the world’s largest mobile market transitions toward digital credentials, the global adoption curve is being fundamentally reshaped, moving away from a niche technology for early adopters toward a mainstream standard. This surge in China, combined with the continued demand for travel-related digital subscriptions, demonstrates that the infrastructure for consumer connectivity has reached a level of maturity that can support hundreds of millions of simultaneous users without significant disruption.
While established markets in North America and Europe remain foundational to the ecosystem, the current year has seen a notable diversification of adoption across South America, Africa, and the Middle East. This geographical expansion is being fueled by an increasing number of affordable smartphones that support digital credentials, making the technology accessible to a broader demographic. Nevertheless, the growth of the digital subscription market remains intrinsically linked to the overall health of the consumer electronics industry, as fluctuations in smartphone shipment volumes can directly impact the rate of new activations. Even with these external pressures, the trend toward digital-first mobile experiences appears irreversible, as users increasingly value the convenience of instant activation and the ability to manage multiple lines without physical cards. For global service providers, the challenge now lies in scaling their customer support and digital onboarding processes to match the rapid influx of new users who expect a seamless experience that traditional models cannot provide.
Pragmatic Approaches to Hybrid Connectivity and Infrastructure
Remarkably, the transition toward digital credentials has not resulted in the immediate decline of traditional physical SIM hardware, which actually grew by six percent during the first half of the current year. This persistence highlights the fact that the telecommunications industry is moving toward a hybrid environment rather than a complete replacement of older technologies. Physical hardware remains the most cost-effective and reliable solution for a wide range of legacy applications and regions where the cost of upgrading to digital-ready devices is still prohibitive. In many industrial sectors, where the lifespan of a device may exceed a decade, the simplicity and familiarity of a physical card offer a level of predictability that some organizations are not yet ready to abandon. This suggests that for the foreseeable future, the market will continue to support a dual-track strategy where both physical and digital options coexist to meet the diverse needs of different industries. Stakeholders must therefore remain adept at managing both types of credentials.
The most effective response to these industry shifts involved a comprehensive reevaluation of lifecycle management and security protocols. Successful organizations recognized that simply enabling a device was insufficient; they prioritized the secure, over-the-air updating of credentials across various international networks to maintain operational integrity. It was critical for enterprises to implement management platforms that could handle the specific complexities of the SGP.32 standard, which simplified the automation of massive sensor deployments. Furthermore, companies that conducted thorough audits of their current device fleets were able to identify which assets benefited most from a transition to digital credentials while maintaining physical hardware where cost-optimization was required. By developing a clear roadmap for this transition, stakeholders avoided the common pitfalls of a fragmented connectivity strategy and ensured their operations remained scalable. These actions ultimately provided the resilience necessary for businesses to navigate the evolving global network landscape.